The available routes to market, which starts on site now rely upon, have also narrowed. The withdrawal of Help to Buy, reduced overseas demand, worsening mortgage affordability and weaker transaction volumes have all combined to increase delivery risk. While sales of completed stock remain relatively positive, this is largely down to a lack of investors buying off plan and domestic buyers preferring to purchase homes that are completed. As a result, new homes are taking longer to sell, while lenders and investors require greater confidence in sales rates and exit strategies. In this environment, certainty can be as valuable as price. To this end, we welcome the government’s announcement of a new equity loan scheme – Your First Move – ahead of next month’s Budget and await further detail.
Looking Ahead
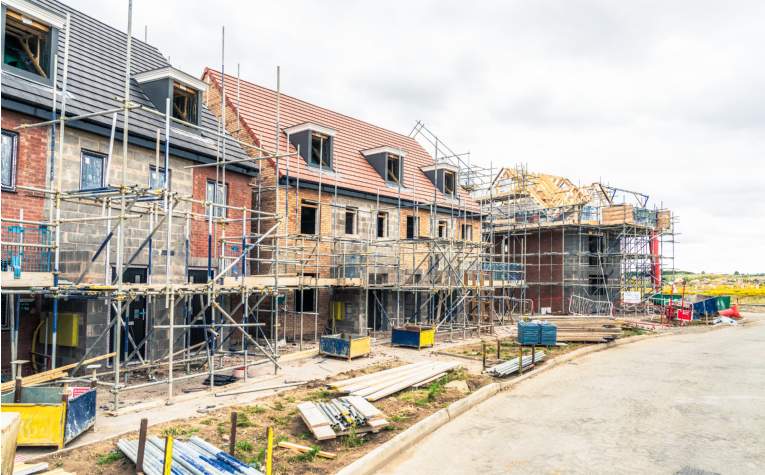
Our research shows that these pressures are already affecting future supply. Private housing starts fell from more than 27,000 in 2017 to around 5,600 in 2025. Build to Rent, affordable housing and co-living have also slowed, and there is currently no single tenure large enough to compensate fully for the wider decline. Even if market conditions improve, the low number of schemes entering the pipeline has already created a future delivery gap.
Bringing sites forward increasingly requires a different delivery model in order to create viable and deliverable projects: multiple sources of capital, multiple tenures and multiple routes to market. Delivery of private homes supports the delivery of affordable housing through Section 106, while Build to Rent, bulk sales and partnerships with affordable housing providers can offer alternative routes. However, each depends on the availability of capital, grant funding and delivery capacity.
The answer is a more sophisticated delivery model. The most successful developments of the next decade are likely to combine multiple tenures, multiple capital sources and multiple routes to market from the outset.
Bringing complex projects to market will therefore require collaboration from all parties from the outset provide more credible and deliverable routes to market. Developers, investors, lenders, affordable housing providers and public authorities need to align earlier around tenure, funding, delivery and risk. Greater flexibility between tenures, targeted public investment, institutional capital and more explicit risk-sharing could provide the confidence needed to move viable schemes forward. Initiatives such as the New Homes Accelerator and ATLAS (Advisory Team for Large Applications) may help unblock sites and address planning capacity, but acceleration can only succeed where the underlying scheme can be made viable, and those who are responsible for delivery have the confidence to start.
London cannot close its delivery gap by waiting for values to rise and build costs to fall. The public sector cannot fund the solution alone. The market has changed structurally, and the way we deliver housing must evolve with it. Collaboration will be fundamental to converting demand into viable, investable and deliverable mixed-use places at scale, which is exactly what London needs.